Over the past couple of months we're notices a notable development in the women's health technology. Companies traditionally focused on physical devices are expanding into digital health, signaling a significant trend in the industry.
Examples? 👇
Elvie, known for its smart breast pumps and kegel trainers, has recently launched Elvie Strong, a free pelvic floor exercise app. This move into software development marks a departure from their hardware-centric approach and highlights the company's evolving strategy.
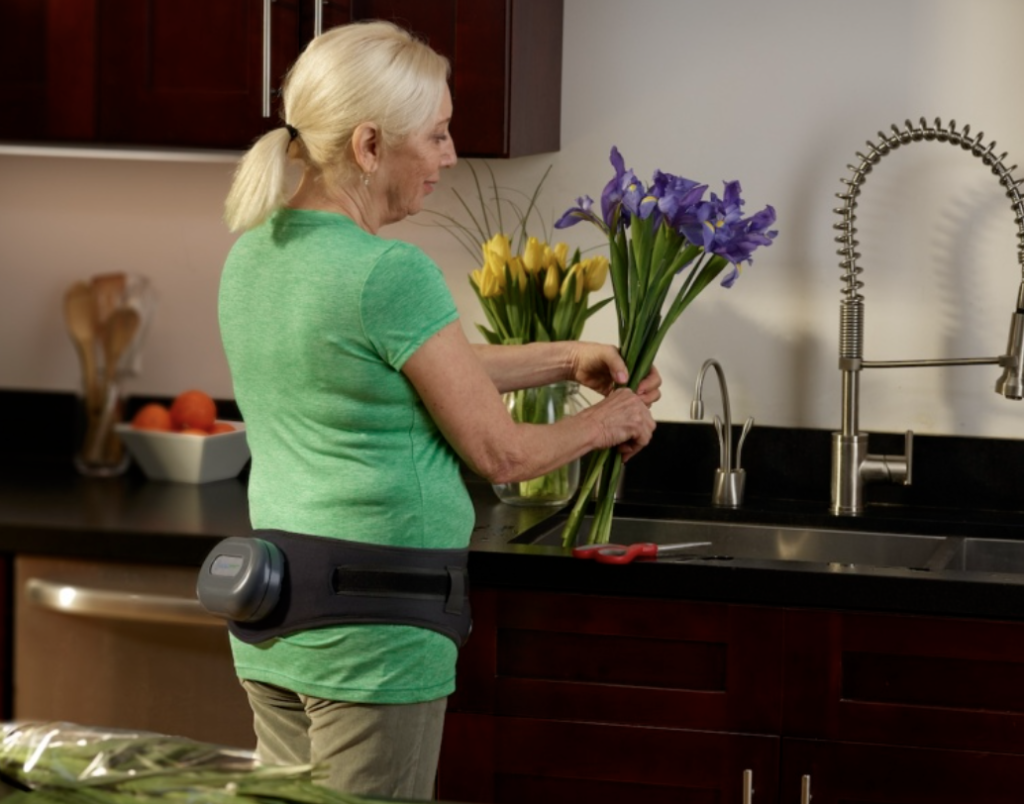
Similarly, Bone Health Technologies (BHT) has acquired Wellen, a startup specializing in digital osteoporosis care. BHT, primarily recognized for its Osteoboost vibration therapy belt (pictured above), is now positioning itself to offer a more comprehensive approach to bone health through this acquisition.
These developments raise an important question: What's driving this expansion into digital health? And is this trend here to stay?
One key factor why medtech companies have their eye on digital health is accessibility. Many advanced medical devices come with a high price tag, especially when sold directly to consumers. Digital services, often offered at lower cost or even for free, provide an easier entry point for potential customers. This approach allows companies to establish relationships with users without requiring a significant upfront investment.
However, the strategy extends beyond sales. These digital platforms serve as valuable data sources, offering insights into user behavior, health trends, and treatment efficacy. For companies aiming to refine their products or target their marketing efforts, this information is invaluable.
Moreover, the overall increasing digitization of healthcare is a driving force. Medtech companies recognize the need to adapt to this changing landscape or risk losing market share. By venturing into digital health, they're not only keeping pace with industry trends but also positioning themselves at the forefront of healthcare innovation.
The trend of medtech companies expanding into digital health adds an interesting dimension to the healthcare M&A landscape.
Historically, digital health has seen a diverse range of acquirers, with medtech firms interestingly enough playing a relatively minor role. According to Rock Health's 2022 Digital Health M&A Report, from 2018 to 2022, digital health companies were primarily acquired by other digital health companies (34%), healthcare services companies (19%), and healthcare IT companies (16%). Medical device companies, surprisingly, found themselves at the bottom of this list.
However, the recent expansion of medtech firms into digital health could potentially alter this dynamic. We might see an uptick in medtech's share of digital health acquisitions, further diversifying the M&A landscape and potentially fostering more integrated health technology solutions.
For women's health, the implications could be transformative. We're already starting to a future where smart medical devices seamlessly integrate with apps that track exercises, offer personalized advice, and share progress reports with healthcare providers. The potential for improved, personalized care is - as many of you will know - significant.
So as the boundaries between medtech, digital health, and traditional healthcare continue to blur, we may be witnessing the emergence of a new paradigm in healthcare delivery. The current trajectory suggests that success in women's health innovation increasingly requires a strong digital component. Whether this trend represents a fundamental shift in care delivery or an evolution of existing approaches remains to be seen. What's clear is that the women's health technology landscape is currently undergoing rapid and significant change, driven by both technological advancements and also changing consumer expectations.